

Know if your edge is real — before you risk a dollar.
Nobody can predict the market. But you can find out whether a strategy has an edge — by replaying it against years of real, minute-by-minute history. Tradetron does that in a few clicks, then hands you an interactive report graded A–F by Claude, net of every cost. History doesn't repeat, but it rhymes.
Trading without an edge is just an expensive way to gamble.
The future is genuinely unpredictable — no backtest changes that. What a backtest does change is whether you're guessing. It answers one question that separates a strategy from a hunch: over hundreds of past days, did this set of rules actually make money after costs — or did it only look good on a lucky week?
Prices never repeat exactly, but conditions recur — trends, mean-reversion, volatility crushes, gap-ups. A rule that profited across many of those regimes is far likelier to hold than one you've only imagined.
A single good month proves nothing. A backtest exposes concentration, drawdowns and win-rate across the whole window — and a Monte-Carlo pass reshuffles your returns 2,000 times to ask: was this edge, or was it luck?
Commissions, slippage and exchange and regulatory fees quietly eat returns. Gross P&L flatters everyone. Every Tradetron backtest is scored on net P&L — so a strategy that only wins before costs can't hide.
From My Strategies to a graded report in minutes.
Any template you build — with Claude, the Advanced Builder, or the wizards — is one click from a backtest. No exports, no spreadsheets, no code.
Open My Strategies, find your strategy, and press the Backtest button on its row. Same rules you'd deploy live — no re-writing.
Choose a date range and capital, and set your cost profile once — brokerage, slippage and statutory charges for your broker and segment.
Every leg is filled at the actual traded price for each minute of the window — real option premiums and OI, not a model — exactly as the live engine would.
In minutes you get an interactive, Claude-graded report — grade, stats, equity curve, drawdowns, Monte-Carlo and a live cost lab.
Most backtesters take a shortcut. Tradetron lives through every minute.
Most fast backtesters are vectorised: they run your signal across the whole price history in one big array sweep. It's quick — and it's stateless. It has no idea what your running P&L is, which legs are still open, or what you decided three bars ago. Tradetron can't work that way, because your strategy's own state drives its next decision.
- Compute signals over the whole series at once — no memory of what happened between bars.
- Can't model a decision that depends on live P&L — "exit everything if the strategy is down $X".
- Trailing stops, re-entries, per-leg repair, dynamic position sizing and set/leg state get faked or dropped.
- The result is a mathematical approximation — not what your rules would actually have done.
- Walks every data point in order, carrying full state — positions, P&L, runtime variables, counters, set & leg status.
- Every condition is evaluated against that live state, exactly as the deploy-time engine would.
- Path-dependent logic — trailing SL, re-entries, hedge repair, P&L-based exits — runs for real, not approximated.
- What you backtest is byte-for-byte what you would have traded.
Because each decision feeds back into your strategy's own state, there is no shortcut and no array trick that gets it right. The only honest way is to step through history one data point at a time — the same engine, the same order of events, the same rules:
A backtest is only as honest as its data.
Tradetron replays real historical prices — minute-resolution OHLC and open interest, including actual option premiums — not a Black-Scholes approximation. Here's what's loaded today, all at 1-minute resolution.
| Market | Granularity | History available | Depth |
|---|---|---|---|
| US ETF and stock optionsSPY, QQQ, IWM, DIA, TQQQ, GLD, AAPL, AMD, AMZN, GOOG, GOOGL, INTC, META, MSFT, NFLX, NVDA, PLTR, TSLA | 1-minute OHLC | Aug 2021 → ends yesterday | 5+ yrs |
| US Index optionsSPX, XSP, NDX, VIX | 1-minute OHLC | Feb 2023 → ends yesterday | 3+ yrs |
● Every market above backtests today, all at 1-minute resolution. US windows can end yesterday. The Backtest dialog sets the latest end date for you.
Option chains: SPX, XSP, NDX, VIX, SPY, QQQ, IWM, DIA, TQQQ, GLD, AAPL, AMD, AMZN, GOOG, GOOGL, INTC, META, MSFT, NFLX, NVDA, PLTR, TSLA.
One report that a fund analyst would recognise.
Not a PDF of numbers — a live, interactive document you can interrogate. Switch the period, toggle gross vs. net, drag the cost sliders, drill into every round-trip.
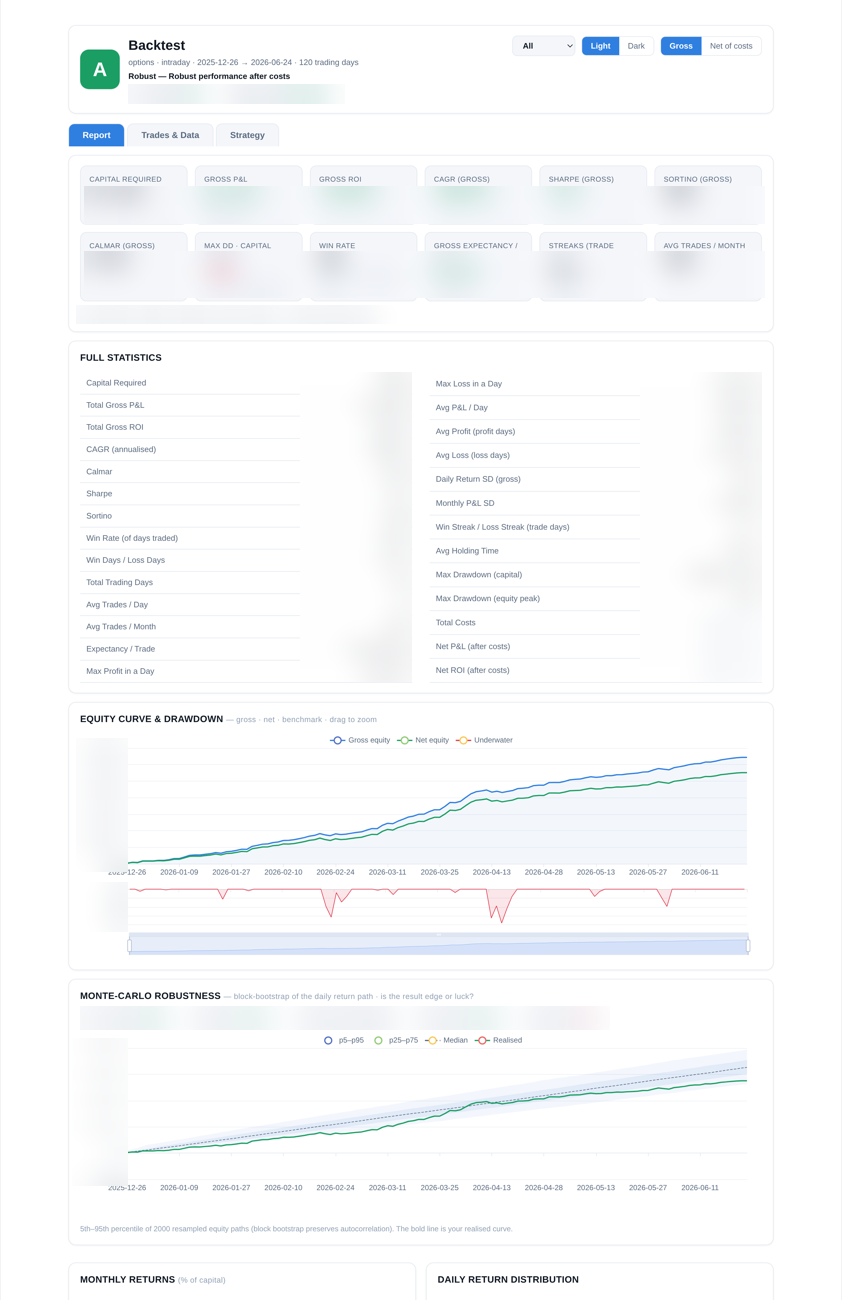
- ◆Claude's grade, up topAn A–F medallion and a one-line verdict — the whole strategy's health in a glance, before you read a single chart.
- ◆Change the period on the flyA dropdown re-slices everything to the last 1M / 3M / 6M / 12M or the full window — stats, charts and grade recompute instantly.
- ◆Gross ↔ net, one toggleFlip between headline gross P&L and the number that actually lands in your account after every charge.
- ◆Monte-Carlo: edge or luck?2,000 bootstrapped equity paths give a probability-of-profit and a realistic best/worst cone around your result.
- ◆Every statistic that mattersCAGR, Sharpe, Sortino, Calmar, expectancy, win/loss streaks, drawdown depth & days underwater, trade-by-trade MAE/MFE.
Why a single letter is worth a thousand rows.
A stats table can bury a fatal flaw in row 30. Claude's grading rubric distils the whole backtest into one honest verdict — scored on net-of-cost performance — and it's fully transparent: you can audit exactly why a strategy earned its letter. No black box, no cherry-picking the gross number.
The score starts at 100 and is docked against four things that quietly wreck real accounts:
The worst peak-to-trough fall on your capital. A 20% max drawdown costs a little; a 50%+ drawdown — the kind that makes you switch the strategy off at the worst moment — costs a lot.
How much of the profit came from a single month. The penalty starts once one month carries roughly 35% of the result and climbs toward 100% — because a strategy resting on a single month is really one lucky event, not an edge. The report flags it and docks the grade.
The share of days (and months) in the green. A strategy that loses on most days needs enormous winners to survive — that fragility shows up here.
Risk-adjusted return after costs. A sub-1 net Sharpe is mediocre for an algo and moves the grade hard; 2+ is genuinely strong. Reward without the risk to earn it doesn't count.
Below the grade, the report lists the risk flags that fired and a short set of hypotheses to test — "a 90-day drawdown suggests no portfolio stop-loss; add a max-loss kill-switch and re-run" — turning a verdict into your next experiment.
A faithful replay — not a time machine.
Tradetron reproduces your logic exactly, but a backtest can only replay what history recorded. A few things genuinely can't be reconstructed — know them, and your expectations stay honest.
Your margin, funds and equity live inside your broker in real time — there's no historical copy to replay, and a backtest doesn't model your broker's real margin.
- Available margin
- Account equity
- Capital deployed
Data that arrives live from an outside source has no stored past, so it can't be reconstructed for a historical run.
- Sentiment / news score
- StockGPT analysis
- Live FX rates
- External API / webhook data
Minute candles carry no bid/ask spread and no intra-minute sequence, so anything that hinges on tick-level timing or the exact spread can't be reproduced.
- Bid / ask price
- The
Sec(sub-minute) keyword - Latency-dependent fills
Strategies that trade on external API or webhook signals can't be backtested. If your strategy fires on alerts pushed from TradingView, a custom webhook, or a third-party API, those past signals were never recorded — there is nothing to replay. Run those in Live Offline instead, and see each signal as it fires.
The engine replays 1-minute bars, not every tick. Inside a minute the exact path of price is invisible, so a stop-loss, target or entry is filled at the minute's price — not the precise instant it would have triggered live. Treat fills as faithful approximations, not tick-perfect: real slippage, partial fills and fast intra-minute spikes can differ. That's exactly why the honest path is always Backtest → Live Offline → Live.
Priced to run, not to ration.
During launch, backtests of US-market strategies (index options, ETFs, US stocks) are unlimited and free for US accounts. No credits, no wallet, no card: build a strategy and run it.
- Full interactive report with Claude's grade, stats, charts and Monte-Carlo
- Unlimited US-market backtests, any window up to 5 years
- Run as many as you need; up to 20 run at once (each sweep variation counts as one)
- Detailed reports stay live for 3 days, then archive to a summary you keep
Testing a SPY iron condor over the last 3 years?
→ Any window up to 5 years is one backtest
→ free for the full run.
Want to compare it on QQQ too?
→ also free.
Test every idea you have and you'll know whether the edge is real before you deploy a single contract.
Before you run your first one.
If the future is unpredictable, what's the point of a backtest?
How realistic are the fills — is this a simulation or real prices?
Can every strategy be backtested?
Does it account for brokerage, slippage and taxes?
Which markets and how far back can I test?
What does the A–F grade actually measure?
How much does it cost?
Find your edge
before the market
finds your account.
A strategy you built this morning can be graded against years of history by lunch.
Risk disclosure. Backtested and simulated results are hypothetical, are generated with the benefit of hindsight, do not represent actual trading, and are not indicative of future results. Any figures on this page — including the sample report and the cost-lab numbers — are illustrative examples of the report format, not a forecast, recommendation, or promise of returns. Trading in securities and derivatives carries a substantial risk of loss and is not suitable for every investor. Historical-data coverage and market availability may change.